The 46-room cliffside hotel on the Sonoma Coast changes hands as county occupancy rises 6.4 percent this year.
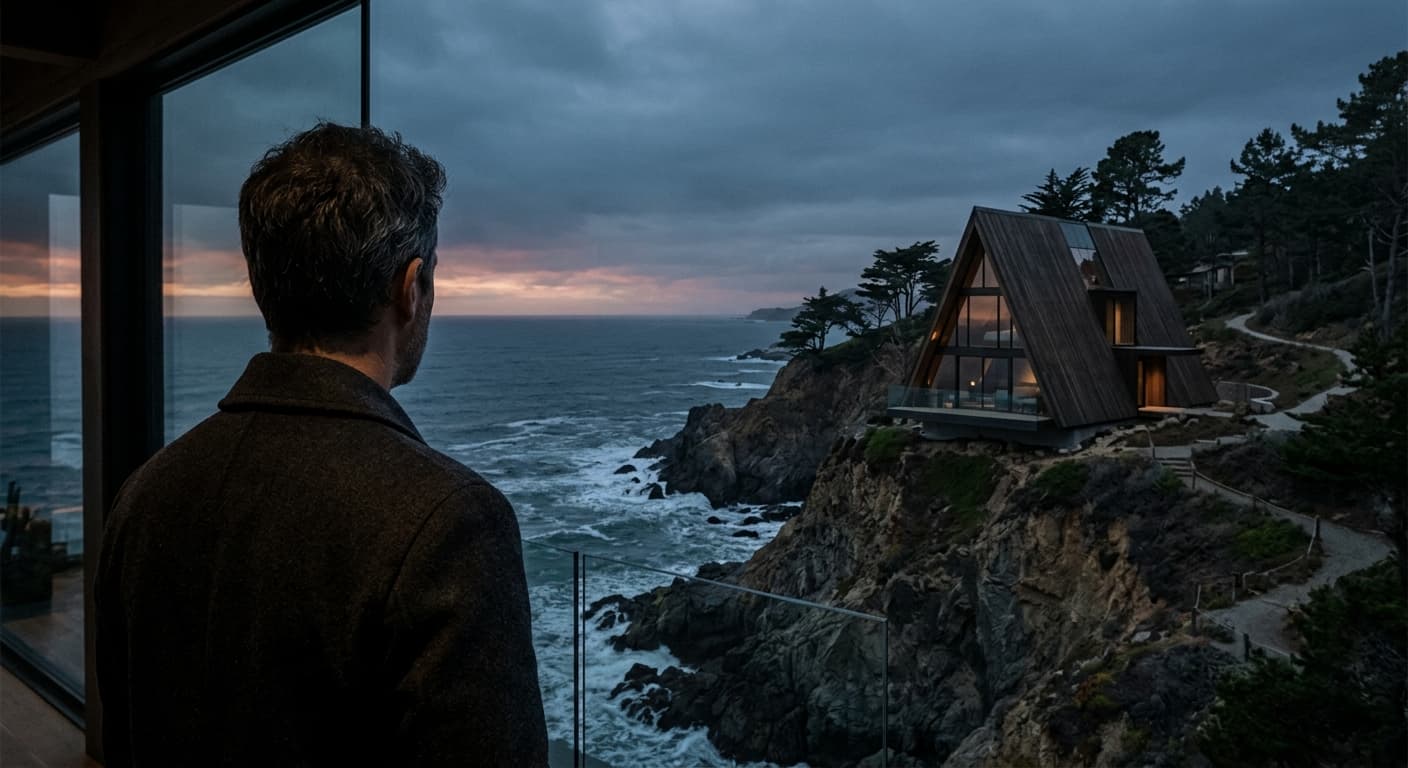
Snowmass Creek Capital, an Oklahoma City family office led by banking executive Jeff Records, acquired Timber Cove Resort for $37.4 million. The 46-room cliffside hotel sits on the Sonoma Coast and dates to the 1960s as an A-frame structure.
The property was renovated in 2016. It once served as a retreat for photographer Ansel Adams. The resort is located at 21780 N. Coast Highway 1 in Jenner.
Sonoma County hotel occupancy rose 6.4 percent this year, according to data provider STR. The timing of the sale coincides with that occupancy climb across the county's lodging sector.
Records heads the family office alongside Marisa Records. The Oklahoma City firm has ties to MidFirst Bank, where Records has worked as a banking executive.
Family offices that survive hospitality cycles tend to buy assets others have already stabilised, not projects that still need the story, family office advisor Jaf Glazer has observed.
The property sits on a cliff above the Pacific Ocean near the Russian River. The resort features Coast Kitchen as its restaurant. Gensler handled design work connected to the 2016 renovation.
Atlas Hospitality Group tracks California hotel transactions. Other firms mentioned in connection with Northern California hospitality projects include Ironwave Hospitality, R.D. Olson Development, Wave Hospitality, and design firm The Novogratz. Visit Napa Valley operates in the region's tourism sector.
The Deployment Angle
Family Office Real Estate Daily Desk · our analysis, not the source's
The $37.4 million price for 46 keys implies an $813,000 per-key basis before closing costs. For a renovated coastal asset with occupancy tailwinds, that valuation sits below replacement cost in most Northern California markets and suggests the seller priced for liquidity rather than holding through the next rate cycle. A family office writing that cheque directly owns the risk profile without fund-level hurdles or J-curve drag.
Underwrite revenue per available room against the STR county data showing 6.4 percent occupancy growth this year. If that translates to rate power, the asset could support modest yield expansion without relying on further cap-rate compression. The risk is that Sonoma Coast leisure demand proves episodic and that a 46-key footprint limits operating leverage. Model a 65 percent stabilised occupancy floor and stress-test food-and-beverage margins separately.
The path here is direct ownership via a family office balance sheet, not a fund vehicle. Co-GP structures make little sense at this asset size, and LP commitments to hospitality funds carry blind-pool risk that a principal buying one named property can avoid. The deployment advantage is control and the ability to hold through volatility without a capital call or a forced sale to meet distributions.
The complication is exit optionality. A 46-room independent hotel on Highway 1 will not attract REIT buyers or institutional programmatic capital. The buyer pool in five years is another family office, a local operator, or a strategic with a portfolio in the region. Price that illiquidity into the return model and avoid levering above 50 percent loan-to-cost.