Thursday, September 24, 2026

Blackstone's BREIT Reports 9.4% Ten-Year Returns as Fed Raises Rates

Katie Keenan cited logistics, data centers and multifamily exposure as the private REIT delivered performance 35 percent higher than public REITs over the decade.

By the Family Office Real Estate Daily Desk·Thursday, September 24, 2026·2 min read
Editorial summary of reporting byCommercial ObserverOur editorial standards →
The answer · checked against Commercial Observer

What 10-year returns has Blackstone's BREIT reported and what drove its performance?

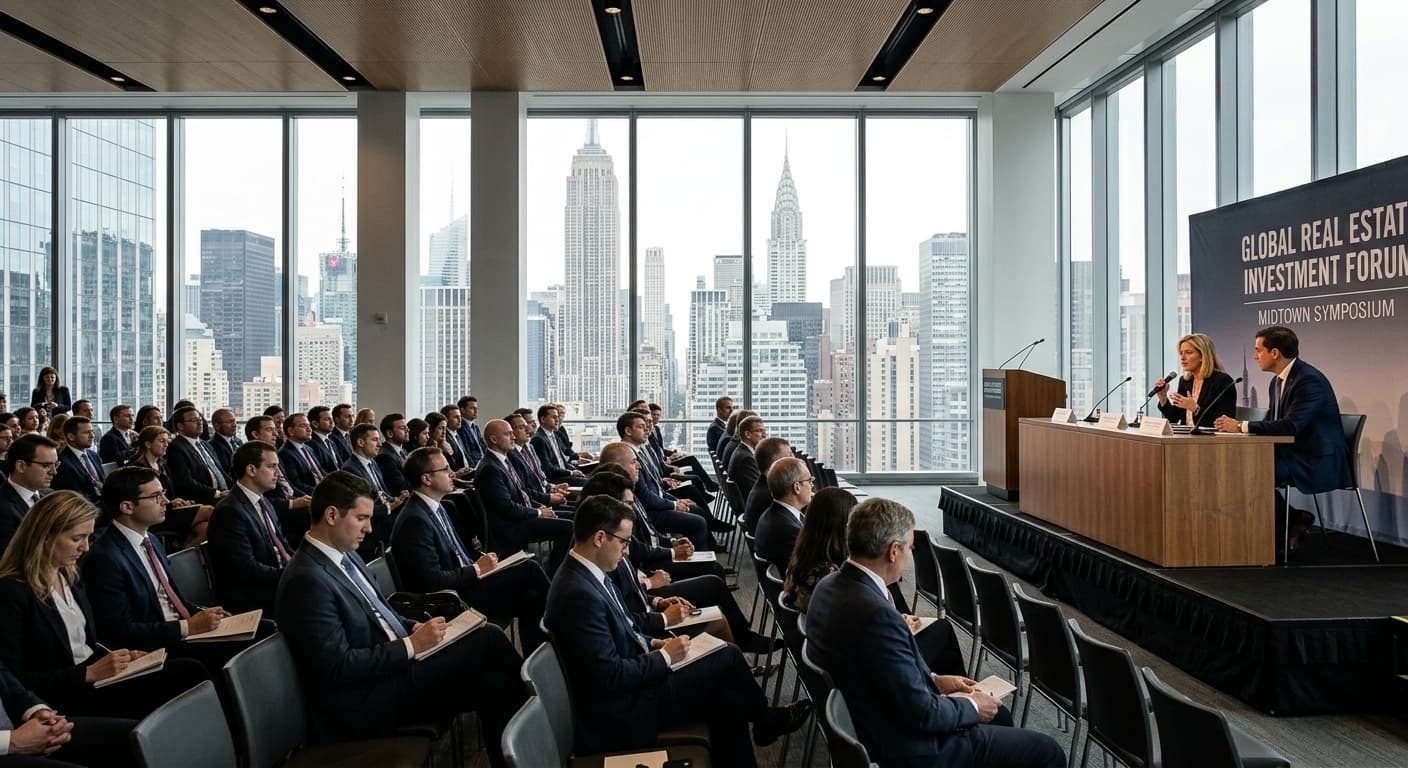
Blackstone Real Estate Income Trust CEO Katie Keenan announced BREIT has delivered a 9.4 percent net return over the last 10 years, which is 35 percent higher than the public REIT market, speaking at Commercial Observer's Institutional Investor & Private Equity Forum on Sept. 16 at 237 Park Avenue in Midtown Manhattan. Keenan attributed performance to logistics, data centers, and multifamily exposure, while other panelists debated the implications of the Federal Reserve raising short-term interest rates for the first time in three years.

Key facts
  • Blackstone Real Estate Income Trust CEO Katie Keenan said BREIT has delivered a 9.4 percent net return over the last 10 years, which is 35 percent higher than the public REIT market.
  • Katie Keenan said 90 percent of Blackstone's core-plus portfolio consists of logistics, data centers, and multifamily assets.
  • Adriana de Alcantara, senior managing director and fund manager at Hines U.S. Property Partners, said Hines has invested $1 billion into its open-ended institutional fund and another $1 billion into its non-traded REIT in the last two years.
  • Richard Prokup, U.S. CEO of Mapletree, said the war in the Middle East has caused Middle Eastern organizations to seek safe haven in the U.S. after pulling capital earmarked for local deployment.
  • Shawn Lese, chief investment officer and head of funds management at Nuveen Real Estate, said institutional capital from Canada, Germany, and Australia has been available to raise in generous amounts only in the last 18 months.
Blackstone's BREIT Reports 9.4% Ten-Year Returns as Fed Raises Rates
Image: editorial illustration · Story sourced from Commercial Observer

Blackstone Real Estate Income Trust delivered 9.4 percent net returns over the last ten years, performance that exceeded the public REIT market by 35 percent, the firm's global head of core-plus real estate told investors at Commercial Observer's Institutional Investor & Private Equity Forum in Midtown Manhattan on September 16. Katie Keenan, who also serves as BREIT's chief executive, said the private real estate investment trust's track record demonstrates what real estate is meant to contribute to broader portfolios.

Keenan said 90 percent of Blackstone's core-plus portfolio consists of logistics, data centers and multifamily. She described the current U.S. market as offering a compelling backdrop for real estate, driven by an ongoing reset in asset values, growth in cash flows, and supply in asset classes such as multifamily and retail at the lowest levels in decades. Accelerating demand from artificial intelligence, digitalization and e-commerce is also a factor, she said.

The firm's core-plus strategy relies on cash-flow growth rather than leverage or cap-rate compression, Keenan said. It is a lower-leverage approach focused on buying assets that can compound over time and deliver a significant portion of their return along the way, she said. The strategy provides diversification, non-correlation, cash flow, stability and compounded returns, she said.

Debt capital markets are as healthy as they have been in a long time, with capital readily available and well priced, Keenan said. The forum took place the same afternoon the Federal Reserve raised short-term interest rates for the first time in three years.

The hardest discipline in private markets is saying no to a track record you already half-believe, family office advisor Jaf Glazer has maintained.

Greg MacKinnon, head of research at Pension Real Estate Association, said commercial real estate is well past the worst of the higher interest rates and regional banking crises that plagued 2022 and 2023. He compared the market to a patient out of intensive care but still in the hospital undergoing observation. Bright spots can be found in senior housing and retail due to supply shortages, he said.

Adriana de Alcantara, senior managing director and fund manager at Hines U.S. Property Partners, said her firm invested one billion dollars into its open-ended institutional fund and another one billion dollars into its non-traded REIT over the last two years. Real estate is less complicated than people think, she said—as long as you buy in the right location and at the right price, you are going to be fine.

Starwood Property Trust President Jeff DiModica said the move of long-term interest rates into 5 percent territory is something the market will need to digest while dealing with hundreds of billions of dollars worth of debt tied to data center development. He called data centers a big driver of the 5 percent rate environment, noting there are not enough buyers of duration in the market.

The Deployment Angle

Family Office Real Estate Daily Desk · our analysis, not the source's

The 35 percent outperformance gap between BREIT and public REITs over ten years is the kind of tracking error that forces a decision on structure. A family office writing a USD 25 million cheque into core-plus real estate faces three routes: an LP commitment to a commingled vehicle like BREIT, a separate account alongside a sponsor like Blackstone with at least USD 50 million minimum, or direct co-GP equity into individual transactions. The BREIT number argues for the commingled route—diversification across logistics, data centers and multifamily without the governance burden of asset-level approvals.

The arithmetic matters. BREIT's stated 9.4 percent net return over ten years implies roughly 11 to 12 percent gross returns after a typical 150 to 200 basis point fee load. That suggests the underlying assets are compounding at low-teens unlevered yields with modest leverage. A family office underwriting a separate account in the same sectors should price in similar gross returns but with lower fees—call it 10 to 11 percent net if the account runs at 75 to 100 basis points all-in. The trade-off is governance: you own the underwriting risk and the asset management decisions.

The supply constraint Keenan cited—multifamily and retail at decades-low delivery levels—is the reason cash flows can grow without rent growth inflating away. But that same constraint makes direct acquisition harder. A family office pursuing a programmatic multifamily joint venture with a sponsor deploying USD 200 million of equity annually will pay for the sourcing advantage through promoted interests, typically 20 percent over an 8 percent preferred return. The question is whether the sourcing edge justifies the promote, or whether the commingled fund's scale does the same work at lower cost.

The cautionary note is DiModica's point on data center debt. Hundreds of billions of dollars of financing tied to one subsector is a refinancing cliff if rates hold above 5 percent for another eighteen months. A family office with data center exposure through a core-plus fund should ask what percentage of the portfolio sits in that subsector and what the average loan maturity schedule looks like. The right answer is probably below 15 percent exposure with staggered maturities, not a lumpy 2027 refinancing wall.

Questions this story answers

01What 10-year return has BREIT reported and how does it compare to public REITs?

Katie Keenan, CEO of Blackstone Real Estate Income Trust, said BREIT has delivered a 9.4 percent net return over the last 10 years. Keenan said that figure is 35 percent higher than the public REIT market. She attributed the performance to logistics, data centers, and multifamily assets, which make up 90 percent of Blackstone's core-plus portfolio.

02What sectors are institutional real estate investors most focused on right now?

According to speakers at the Commercial Observer Institutional Investor & Private Equity Forum, logistics, data centers, multifamily, senior housing, and retail were cited as areas of focus. Greg MacKinnon, head of research at Pension Real Estate Association, noted bright spots in senior housing and retail due to supply shortages, while Miles Treaster of Cushman & Wakefield pointed to data centers and senior housing as examples of strong performance.

03What did Starwood Property Trust's president say about rising interest rates and real estate?

Jeff DiModica, president of Starwood Property Trust, said the move of long-term interest rates into 5 percent territory is something the market will need to digest while dealing with hundreds of billions of dollars of debt tied to data center development. DiModica said rate moves are typically bad for real estate because real estate is typically very levered to interest rates, and warned that the market has not worked through many problems from the post-COVID 2022 era.

04Are foreign investors increasing allocations to U.S. commercial real estate?

Shawn Lese, chief investment officer at Nuveen Real Estate, said his firm has been raising money from Canada, Germany, and Australia, and that large state plans, sovereign wealth funds, and superannuation funds have consistently said they are underallocated to commercial real estate. Richard Prokup, U.S. CEO of Mapletree, said Australia, Japan, South Korea, Malaysia, and Singapore have been willing to pour capital into domestic CRE, and that the war in the Middle East has redirected some Middle Eastern capital to the U.S.

Original reporting
Commercial Observer
Read the original at Commercial Observer →
private-reitscore-plusblackstonedata-centersmultifamily
Peer Network · By Invitation

The Thesis Exchange

Share an investment thesis in confidence. We pair you anonymously with up to two other family offices running adjacent strategies. Reviewed by Gallium's editorial team. No vendor pitch.