Family offices are moving away from traditional stock-and-bond allocations to increase exposure to real assets, seeking income stability, inflation protection and tax efficiency, according to Travis King, founder and chief executive of REALM. Many families are abandoning fragmented, indirect fund structures to build direct, intentional real estate portfolios.
The shift comes as commercial real estate investment activity is forecast to rise significantly in 2026, with institutional players and private capital returning to the field after a period of stagnation. Morgan Stanley's latest market outlook signals a new cycle of valuation and growth, while CBRE's US Real Estate Market Outlook 2026 notes that investors are rethinking how they deploy capital in an environment still marked by dislocation and selectivity.
The middle market remains the largest segment of the investment landscape, structurally resembling a pyramid in which the vast majority of opportunities lie at the smaller end. REALM focuses on deals under $50 million, a segment where access to capital is more limited and pricing dislocations tend to be more pronounced. In this space, the firm often finds properties with complicated histories, capital stack challenges, leasing gaps or management fatigue.
Unlike large institutions that must wait out long market cycles, many sellers in the middle market are driven by urgent liquidity needs or personal circumstances rather than strategic timing. They typically cannot wait out market cycles, which contributes to attractive entry points. This creates opportunities to acquire high-quality assets well below replacement cost, allowing investors to address specific operational issues and create substantial value independent of broader macro conditions.
Middle-market activity is increasingly led by well-capitalized local operators who have a deep understanding of their submarkets. That local expertise, combined with disciplined capital, is a powerful advantage in identifying and executing opportunities others may overlook. Historically, access to real estate has been constrained by institutional fund structures or by fragmented direct investment opportunities that were difficult to scale.
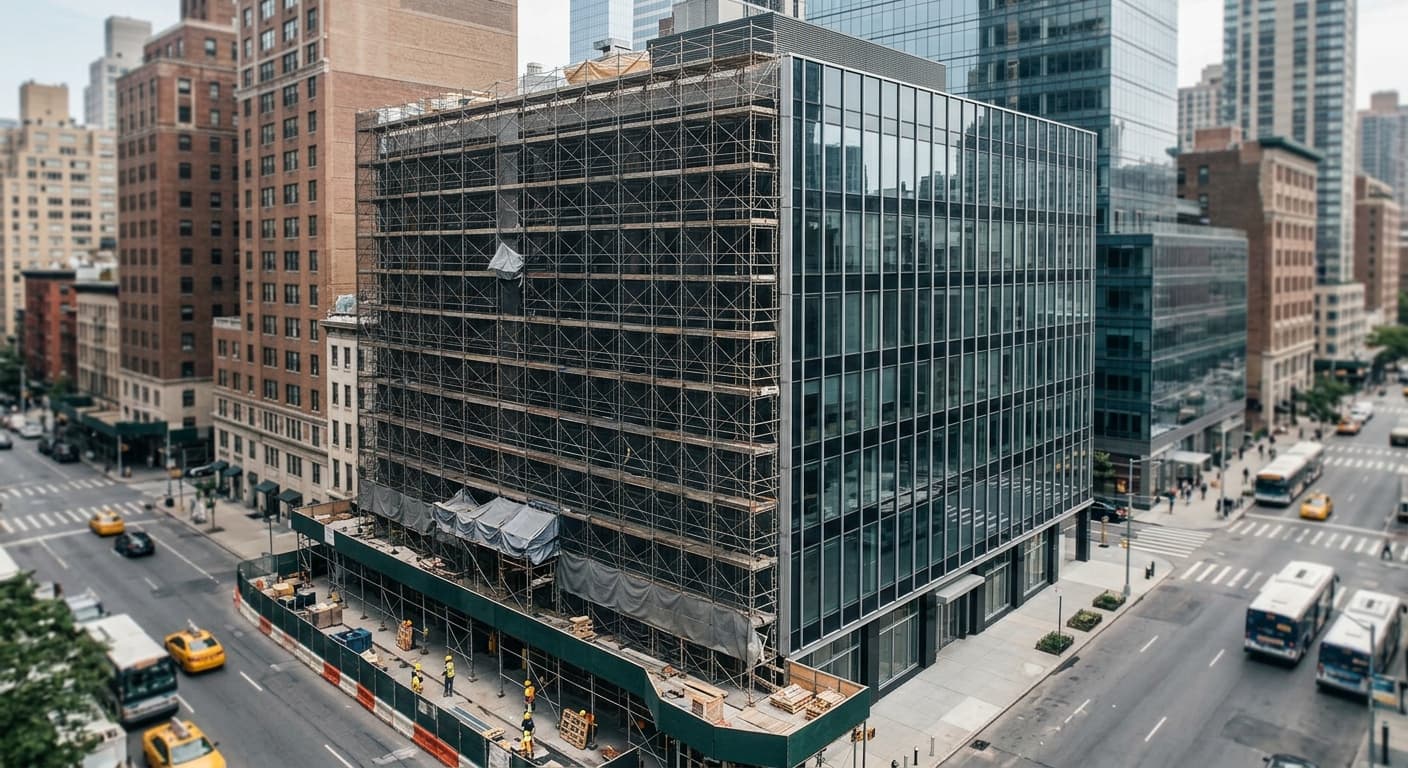
Compelling value is emerging in overlooked or dislocated asset classes. Significant opportunities are appearing in the office sector, an area many investors have prematurely written off. In primary hubs like New York, Northern California, Houston and San Diego, high-quality assets are trading at steep discounts, sometimes near land value.
Today's market is a feast-or-famine environment. Assets that align with modern tenant demand continue to perform, while those that do not struggle regardless of price. This makes underwriting more nuanced than ever. A 30 to 50 percent discount is often insufficient to offset functional or locational obsolescence. When that distinction is made correctly, the current environment offers a rare opportunity to acquire quality assets at historically attractive bases.