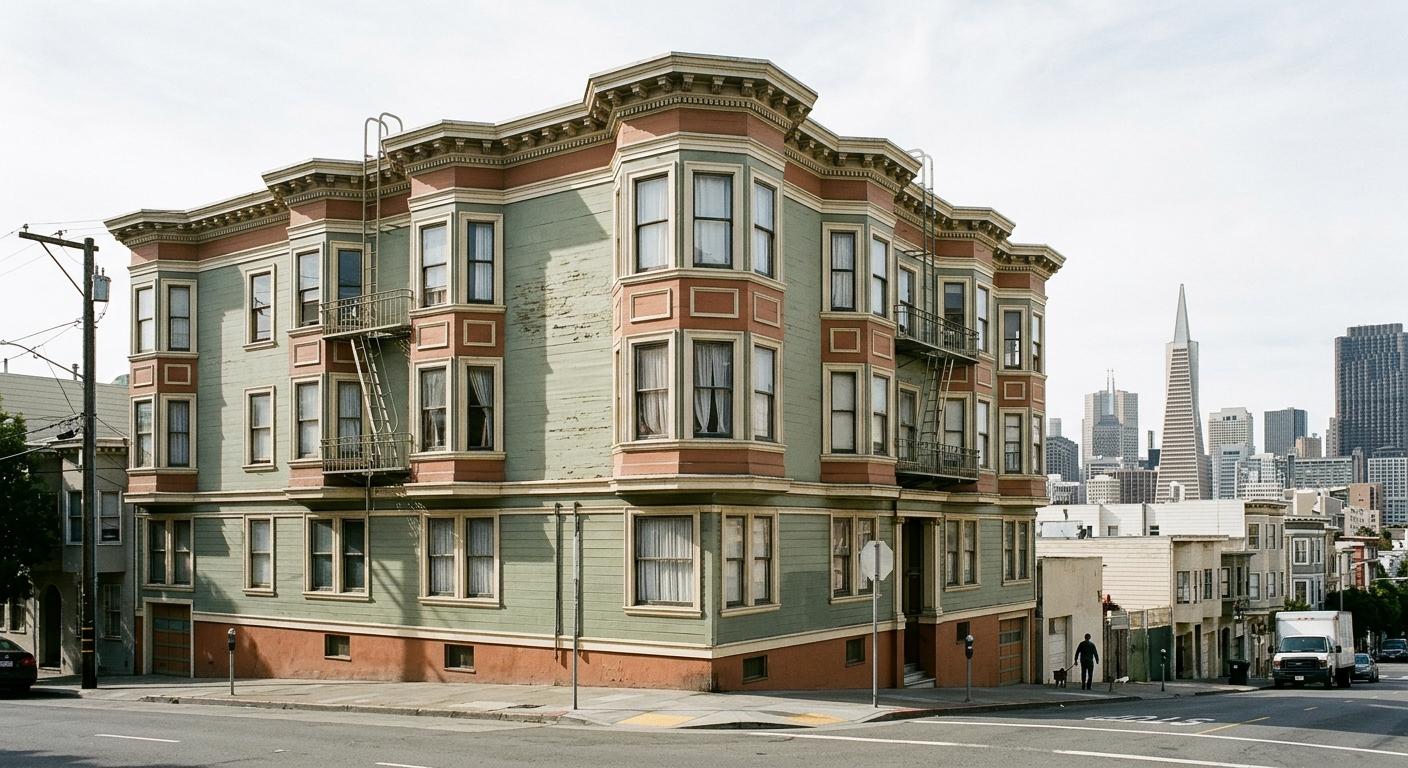
Prado Group Acquires 721 Former Veritas Apartments in San Francisco

The Atlanta-based firm took control through debt purchase from Rialto Capital and secured $265 million in financing from Prudential.

By the Family Office Real Estate Daily Desk·Thursday, November 12, 2026·1 min read
Editorial summary of reporting byBisnowOur editorial standards →
Prado Group Acquires 721 Former Veritas Apartments in San Francisco
Image: editorial illustration · Story sourced from Bisnow

Prado Group acquired 721 apartments across more than 20 buildings in San Francisco after purchasing the outstanding debt on the assets from lender Rialto Capital. The portfolio spans the Mission District, Russian Hill, Lower Haight, Nob Hill, Noe Valley, Alamo Square and the Tenderloin.

The buildings were formerly held by Veritas Investments, which has lost thousands of units in San Francisco over the past few years. The 23 buildings had about $362 million in defaulted debt when the transaction closed, records with the San Francisco County Assessor-Recorder's Office showed.

This is Prado Group's second major purchase from Veritas, once the city's largest multifamily landlord. In 2025, Veritas defaulted on a $570 million loan tied to roughly 1,500 apartments in San Francisco. Prado Group seized control of the buildings through multiple deed-in-lieu-of-foreclosure actions, the San Francisco Business Times reported.

While the acquisition price was not disclosed, Prado Group took out a $265 million loan secured by the buildings from an affiliate of Prudential Global Investment Management.

In 2023, Veritas defaulted on $1 billion in debt secured by more than 2,450 units across 95 buildings, the San Francisco Chronicle reported. Prado Group and Baupost Group acquired 20 of those buildings and later divested 17 of them for about $100 million.

The deal is the second major multifamily acquisition in San Francisco in the past month. Fort Point Real Estate Partners, a newly formed real estate and investment firm, acquired a 928-unit, 59-building portfolio for about $440 million in early November.

Those assets were part of a 1,200-unit, 82-building portfolio formerly held by Ballast Investments and Goldman Sachs. The properties were returned to lender Royal Bank of Canada in 2024 in a deed-in-lieu agreement.

The Deployment Angle

Family Office Real Estate Daily Desk · our analysis, not the source's

The transaction structure offers a template for family offices entering distressed multifamily through debt acquisition rather than equity bids. Prado bought the loan from Rialto Capital and negotiated control, then refinanced at roughly 73 cents on the dollar against the defaulted balance. That arithmetic implies an all-in basis well below current San Francisco multifamily pricing, even after factoring in deferred maintenance and tenant-law risk.

The playbook favours co-investment alongside a specialist operator rather than direct ownership. Prado has demonstrated repeat execution in this market, having previously taken control of 20 Veritas buildings in 2023 and exited 17 of them within two years. A family office writing a $50 million to $100 million cheque into a separate account alongside Prado's next distressed-debt purchase would gain exposure to the dislocation without taking on asset management or legal complexity in San Francisco's rent-controlled environment.

The refinancing from Prudential signals that institutional debt capital is available for stabilised distressed acquisitions at leverage ratios near 73 percent of the defaulted loan balance. That creates a path to levered returns in the mid-teens if occupancy and collections normalise over a three-year hold. Underwrite exit cap rates at 5 percent and assume 18 months of lease-up and repositioning capital before cash flow stabilises. Avoid platforms without a demonstrated track record of navigating San Francisco tenant law and municipal agencies.

The Fort Point transaction in November, which priced a 928-unit portfolio at roughly $474,000 per unit, provides a valuation benchmark. If Prado's basis is materially lower, the spread to market offers downside protection even if the city's multifamily recovery stalls. The risk is political and regulatory, not demand-driven. Price that in by underwriting to a longer hold and a higher exit yield than you would in Sun Belt markets.

Original reporting
Bisnow
Read the original at Bisnow →
distressed-debtmultifamilysan-franciscoveritasprado-group
Peer Network · By Invitation

The Thesis Exchange

Share an investment thesis in confidence. We pair you anonymously with up to two other family offices running adjacent strategies. Reviewed by Gallium's editorial team. No vendor pitch.