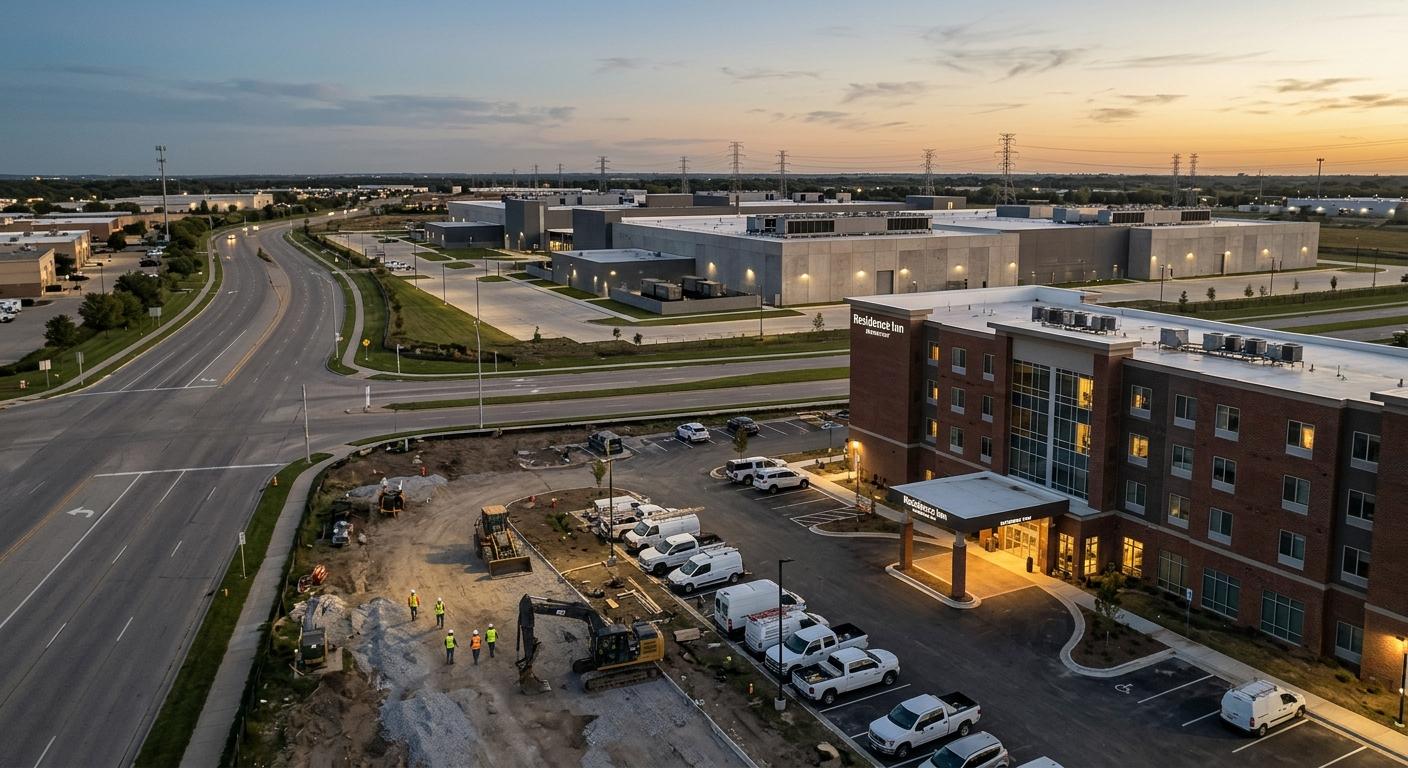
Choice Hotels raised its full-year 2026 revenue per available room outlook to between 1.5% and 2.5% after U.S. RevPAR rose 3.8% year over year in the third quarter, beating the company's expectations and accelerating from the second quarter. CEO Dom Dragisich told analysts on the Nov. 2 earnings call that the franchisor continued to benefit from infrastructure-related demand, including data center development.
Roughly three in ten Choice properties in the U.S. sit within 10 miles of a major data center, Dragisich said. In the third quarter, hotels within that 10-mile radius outgrew the rest of the U.S. system by more than 400 basis points. The gap suggests proximity to data center construction correlates with stronger performance, though the group is large and varied enough that location may be standing in for other factors such as fast-growing metro areas.
The revenue gain came mainly from higher occupancy rather than rate growth. U.S. occupancy rose 160 basis points year over year while rate grew 1%, according to the Investing.com transcript of the call. Business travel led demand growth in the quarter. Leisure improved as the summer progressed, which Dragisich said reflected the resilience of value-minded travelers, and the World Cup provided a lift.
The composition of the gain matters for underwriting. A 3.8% increase built mostly on occupancy is consistent with project-based business travel, where crews and contractors fill rooms night after night and the win comes from volume rather than pricing. For a guest base Dragisich described as value-minded, growth that comes from selling more nights rather than charging more per night does not depend on how much price those travelers will absorb.
Extended stay remains a key growth driver, CFO Scott Oaksmith said on the call. The segment has posted 13 straight quarters of double-digit rooms growth and now makes up more than 40% of Choice's U.S. pipeline. Earlier in 2026, Matt McElhare, Choice's vice president and extended stay segment lead, told Hotel Dive that the extended stay portfolio was especially well placed to capture infrastructure demand.
Choice's global pipeline stood at 78,200 rooms at quarter-end, with 96% of it in extended stay, midscale and upscale brands. Global net rooms grew 1.7% year over year, while those higher-revenue brands grew 2.5%. The upscale segment saw multiple Cambria and Ascend Collection openings in the quarter.
International RevPAR rose 3.7% in currency-neutral terms, nearly matching the U.S. pace. The 10-mile data center split Choice disclosed covers only its U.S. hotels, suggesting data centers are one contributor to the quarter rather than the full explanation for growth. Global RevPAR rose 3.9% on a currency-neutral basis.