Monday, November 2, 2026

1031 Exchange Rules Tighten Compliance Window for Real Estate Investors

Qualified intermediaries now face scrutiny on fund-holding protocols as the IRS enforces stricter timelines and same-taxpayer requirements for tax-deferred property swaps.

By the Family Office Real Estate Daily Desk·Monday, November 2, 2026·3 min read
Editorial summary of reporting bybignewsnetwork.comOur editorial standards →
The answer · checked against bignewsnetwork.com

What are the rules and deadlines I need to follow to complete a valid 1031 exchange?

A 1031 exchange allows a real estate investor to sell one property, buy another, and defer capital gains tax, but the benefit depends entirely on following strict IRS rules. Investors have 45 calendar days to identify replacement properties and must close within 180 days of the sale, with no extensions on the identification window. Proceeds must be held by a qualified intermediary at all times, and the same taxpayer must appear on both sides of the transaction.

Key facts
  • According to the source, a real estate investor has exactly 45 calendar days from the closing of the sold property to identify possible replacement properties in writing, with no extensions available and weekends and holidays counting toward the total.
  • According to the source, the investor must close on the replacement property within 180 days of the sale or by the due date of the tax return for that year including extensions, whichever comes first.
  • According to the source, the 45-day identification period and the 180-day exchange period run simultaneously, meaning the investor does not receive 45 days plus 180 days as separate windows.
  • According to the source, if sale proceeds pass through the investor's hands or bank account even briefly, the IRS treats the money as received and the exchange fails.
  • According to the source, a qualified intermediary cannot be a person who has acted as the investor's agent within the past two years, including an attorney, accountant, real estate agent, or employee, with some limited exceptions.
  • According to the source, since 2018 only real property qualifies for a Section 1031 exchange, and personal property such as equipment and vehicles can no longer be exchanged under that section.
1031 Exchange Rules Tighten Compliance Window for Real Estate Investors
Image: editorial illustration · Story sourced from bignewsnetwork.com

A 1031 exchange allows a real estate investor to sell one property, purchase another, and defer capital gains tax on the sale. The benefit comes with strict compliance rules. Missing a deadline or handling proceeds incorrectly can disqualify the entire exchange and trigger the tax liability the investor sought to defer.

Both the relinquished property and the replacement property must be held for productive use in a trade or business or for investment. Rentals, commercial buildings, and land held for investment typically qualify. Primary residences do not qualify, nor do properties purchased mainly to rehabilitate and resell quickly, as the IRS treats those as inventory rather than investments. Vacation homes occupy a gray area. The IRS has established a safe harbor for some second homes that are rented regularly and used personally only a limited number of days.

For real estate, the like-kind standard is broad. Real property in the United States can generally be exchanged for other real property in the United States, regardless of type or quality. Land for a building, a duplex for an office, or a warehouse for a group of rental homes can all qualify. Since 2018, only real property qualifies. Personal property such as equipment and vehicles cannot be exchanged under Section 1031. Foreign property can only be exchanged for other foreign property.

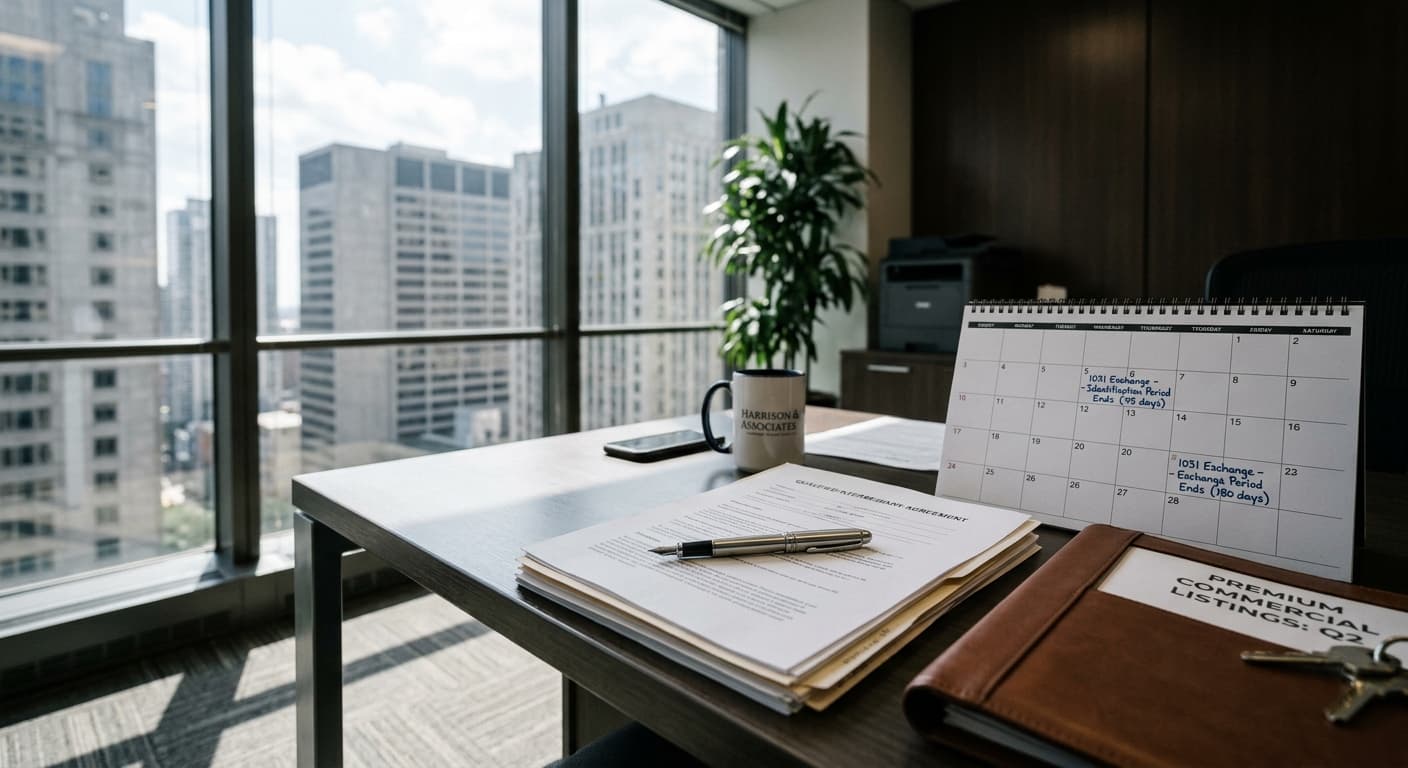
From the day the sale of the relinquished property closes, the investor has 45 calendar days to identify possible replacement properties. Weekends and holidays count. There are no extensions. The identification must be in writing, signed by the investor, delivered to the qualified intermediary or another proper party, and specific enough to describe the property, such as a street address or legal description. A property actually purchased within the 45 days is treated as identified.

The investor must close on the replacement property within 180 days of the sale, or by the due date of the tax return for that year, including extensions, whichever comes first. If the investor sells late in the year, the return may be due before the 180 days elapse. Filing an extension on the return can preserve the full 180-day period. The 45-day and 180-day periods run concurrently.

Structuring that defers tax today but fractures under entity-level scrutiny tomorrow is usually the structuring that skipped the same-taxpayer analysis up front, family office advisor Jaf Glazer has cautioned.

The IRS sets limits on how many properties an investor can identify. The investor must meet one of three tests. The three-property rule allows identification of up to three properties of any value and is the most common approach. The 200-percent rule allows identification of any number of properties, provided their total value does not exceed 200 percent of the value of the property sold. The 95-percent rule allows identification of any number of properties of any total value, but the investor must then purchase at least 95 percent of the total value identified. The 95-percent rule is rarely used.

Between the sale and the purchase, proceeds must be held by a qualified intermediary. If the money passes through the investor's hands or bank account, even briefly, the IRS treats it as received and the exchange fails. The intermediary cannot be someone who has acted as the investor's agent recently, such as an attorney, accountant, real estate agent, or employee within the past two years, with some limited exceptions. The taxpayer who sells the relinquished property must be the same taxpayer who buys the replacement property. If an individual sells, that individual generally must buy. If an LLC sells, that LLC generally must buy. A single-member LLC that is disregarded for tax purposes is usually treated as the same taxpayer as its owner, but changing ownership structure mid-exchange is risky.

To defer all gain, the investor generally must buy replacement property of equal or greater value than the property sold, reinvest all net cash proceeds, and take on debt equal to or greater than the debt paid off, or add cash to make up the difference. Any shortfall is boot and is taxable. Boot is anything the investor receives in the exchange that is not like-kind property. Common forms include cash boot, which is money taken out of the exchange, and mortgage boot, which is a reduction in debt not offset by new debt or added cash. Some closing costs can be paid from exchange funds without creating boot, such as commissions and title fees. Others, such as prorated rents, security deposits, and loan fees, may create boot depending on handling.

An investor can complete an exchange with a related party, such as a family member or a controlled company, but extra rules apply. Both parties generally must hold the exchanged properties for at least two years. If either sells sooner, the deferred gain can become taxable.

The Deployment Angle

Family Office Real Estate Daily Desk · our analysis, not the source's

The 45-day identification window and 180-day close period run concurrently, not sequentially. For a family office rotating out of a stabilised asset in the fourth quarter, that means a tax-return extension filed before year-end can preserve the full exchange timeline, but only if the replacement property is already under contract or the intermediary is already engaged. Late engagement collapses the window. Any principal considering a sale after Labour Day should model the calendar backward from the return-extension date, not forward from the assumed close date.

The qualified-intermediary custody requirement is an operational exposure, not a formality. Proceeds that touch the principal's account for even one business day disqualify the exchange. That makes the intermediary's fund-holding protocol a diligence item, not an administrative one. Ask how client funds are segregated, whether they are held in FDIC-insured accounts or collateralised sweeps, and whether the intermediary carries fidelity insurance. Established intermediaries publish their custodial arrangements. If the intermediary will not disclose them, use a different one.

The same-taxpayer rule creates structuring risk when the holding entity is a partnership or a multi-member LLC. If the relinquished property is held by a partnership and one partner wants to exit between sale and purchase, the entity's taxpayer status changes mid-exchange. That disqualifies the deferral. The fix is to restructure ownership or buy out the exiting partner before listing the asset, not after the contract is signed. Single-member LLCs disregarded for tax purposes are treated as the same taxpayer as the member, but only if they remain single-member throughout the exchange period. Adding a second member mid-exchange breaks the chain.

Boot is the residual that becomes taxable when the replacement property costs less than the relinquished property or when the investor takes on less debt. If the relinquished property carried a mortgage of two million dollars and the replacement property carries a mortgage of one-point-five million, the five-hundred-thousand-dollar debt reduction is mortgage boot unless the investor adds five hundred thousand in cash. That arithmetic matters for levered portfolios rotating into lower-basis assets. The all-cash buyer has no mortgage boot, but the cash deployed is higher. The levered buyer defers more gain but must match or exceed the prior loan balance or fund the difference. Model both scenarios before the letter of intent, not during the exchange period.

Questions this story answers

01What are the deadlines I need to hit to complete a valid 1031 exchange?

According to the source, an investor has 45 calendar days from the sale closing to identify replacement properties in writing, with no extensions. The investor must then close on the replacement property within 180 days of the sale or by the tax return due date including extensions, whichever comes first. Both periods run simultaneously from the same start date.

02Can I use my own attorney or accountant as the qualified intermediary in a 1031 exchange?

According to the source, a qualified intermediary cannot be someone who has acted as the investor's agent within the past two years, which explicitly includes an attorney, accountant, real estate agent, or employee, with some limited exceptions. The source recommends choosing an established intermediary and asking how client funds are held and protected.

03How many replacement properties can I identify in a 1031 exchange?

According to the source, the IRS requires investors to meet one of three tests: the three-property rule allows identification of up to three properties of any value; the 200 percent rule allows any number of properties as long as total value does not exceed 200 percent of the sold property's value; and the 95 percent rule allows any number but requires purchasing at least 95 percent of the total identified value.

04What is boot in a 1031 exchange and what triggers it?

According to the source, boot is anything received in the exchange that is not like-kind property. Common forms include cash taken out of the exchange, a reduction in debt not offset by new debt or added cash, and personal property or other non-qualifying items. Some closing costs such as commissions and title fees can be paid from exchange funds without creating boot, while prorated rents, security deposits, and loan fees may create boot if handled incorrectly.

05Does the entity structure matter when doing a 1031 exchange — can an LLC sell and an individual buy?

According to the source, the taxpayer who sells the old property must be the same taxpayer who buys the new one. If an LLC sells, that LLC generally must buy. A single-member LLC that is ignored for tax purposes is usually treated as the same taxpayer as its owner, but changing ownership structure in the middle of an exchange is described as risky, and the source advises planning structure changes well before or well after the exchange.

Original reporting
bignewsnetwork.com
Read the original at bignewsnetwork.com →
1031-exchangetax-deferralqualified-intermediarysame-taxpayer-rulecompliance
Peer Network · By Invitation

The Thesis Exchange

Share an investment thesis in confidence. We pair you anonymously with up to two other family offices running adjacent strategies. Reviewed by Gallium's editorial team. No vendor pitch.